 Trendsmill
Bank of America has been ordered to pay more than $1.2 billion in penalties after US regulators found serious failures in its efforts to prevent financial crime and comply with sanctions requirements.
The enforcement action puts one of America’s largest banks under the microscope over the safeguards it uses to identify suspicious transactions and prevent the financial system from being exploited by criminal networks.
The US Treasury Department said the penalties covered failures linked to anti-money laundering obligations and apparent breaches of sanctions imposed on individuals, organisations and entities subject to US restrictions.
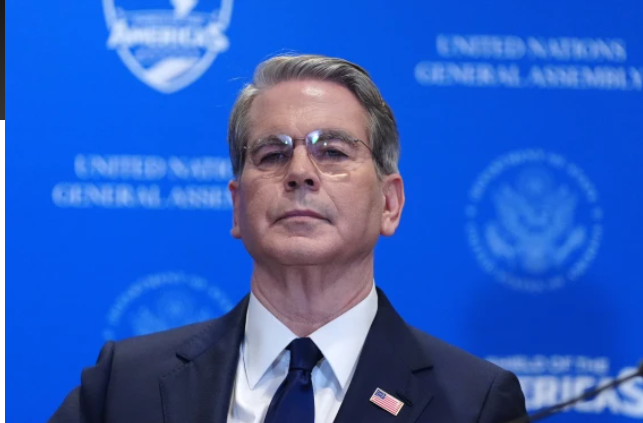
Treasury Secretary Scott Bessent said the action underscored the responsibility of financial institutions to protect the integrity of the banking system, regardless of their size or influence.
The penalties include a $1.2 billion assessment by the Financial Crimes Enforcement Network, known as FinCEN, over the bank’s handling of financial crime risks. A separate $750 million civil penalty was imposed by the Office of the Comptroller of the Currency, according to the government’s announcement.
The bank also agreed to pay about $11.6 million to resolve a separate sanctions enforcement case involving hundreds of apparent violations.
The alleged sanctions breaches concerned transactions associated with restricted parties and jurisdictions, including connections to Russia, Iran, narcotics and terrorism-related programmes. The case also raised concerns about the bank’s sanctions-screening processes and its handling of alerts involving potentially prohibited payments.
At the centre of the action is the Bank Secrecy Act, a US law that requires financial institutions to maintain systems for detecting suspicious activity and reporting potential money laundering to the authorities.
Regulators rely on these controls to identify transactions that could be connected to criminal proceeds, sanctions evasion or threats to national security.
Bank of America said it had cooperated with regulators to resolve the matters, which included issues connected to a 2024 regulatory order.
The bank said financial crime compliance was a serious responsibility and pointed to investments in technology and a workforce dedicated to detecting and preventing illicit financial activity. It also acknowledged that work to address regulators’ concerns was continuing.
The case adds to a series of major US enforcement actions against financial institutions over compliance failures. TD Bank agreed to a roughly $3 billion resolution with US authorities in 2024, while cryptocurrency exchange Binance reached a settlement worth about $4 billion in 2023.