 Trendsmill
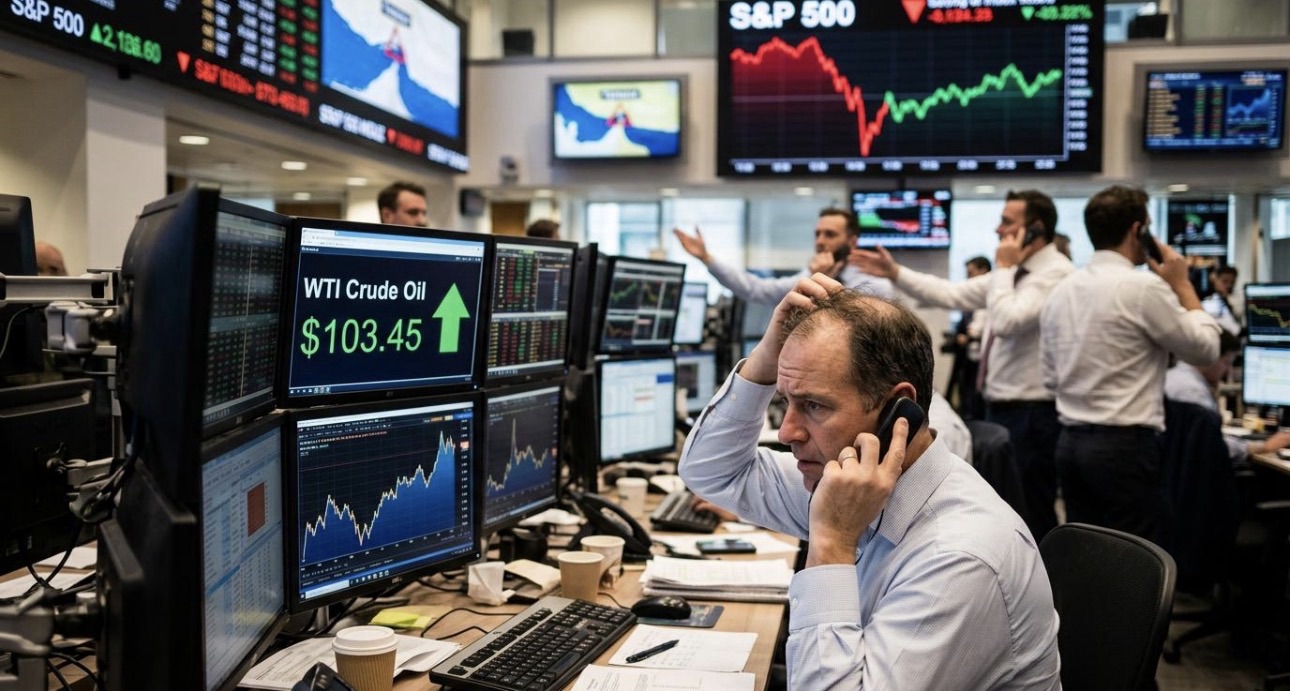
Global equities opened the week under pressure after a fresh jump in oil prices intensified fears that the escalating Middle East conflict could fuel inflation and force central banks to keep interest rates higher for longer.
The latest sell-off puts investors in a difficult position. Markets that had been positioning around the possibility of easier monetary policy are now having to price in a new threat: an energy shock capable of pushing consumer prices higher while simultaneously weighing on economic growth.
Brent crude surged above $107 a barrel on Monday as concerns over disruptions to oil supplies and shipping routes in the Middle East intensified. The move immediately sharpened the focus on the potential economic cost of the conflict and its ability to spill into financial markets.
The oil surge is particularly significant because energy costs feed into almost every part of the economy. More expensive crude can raise transportation and production expenses, increase household fuel bills and ultimately put upward pressure on consumer prices.
That creates a difficult calculation for central banks.
Policymakers attempting to bring inflation down could find themselves facing fresh price pressures just when investors had begun looking ahead to lower borrowing costs. A prolonged increase in energy prices could therefore delay rate cuts or even revive expectations of additional tightening.
The United States is already showing signs of this shift. Stronger-than-expected inflation data, combined with the jump in oil prices, has led major financial institutions to increase their expectations of a Federal Reserve rate hike in September.
Higher US rates could create another problem for emerging markets.
When American yields rise, dollar assets can become more attractive to international investors. Capital can consequently move away from riskier markets, putting pressure on emerging-market stocks and currencies.
The impact of the oil shock will not be uniform. Major crude exporters could benefit from stronger oil revenues, while economies heavily dependent on imported energy may face rising import costs, weaker currencies and renewed inflationary pressure.
Investors are also watching Asian and European equities closely. Markets across both regions have been exposed to the same combination of geopolitical uncertainty, energy-price volatility and shifting expectations about global monetary policy.
The biggest question now is whether the oil-price surge proves temporary or develops into a sustained shock.
A quick easing of tensions could allow crude prices and inflation expectations to retreat. A prolonged disruption, however, could create a much more complicated environment for central banks and investors.
That leaves global stocks exposed to further swings as markets track developments in the Middle East, movements in crude prices and the next signals from major central banks.
The conflict is no longer being priced solely as a geopolitical crisis. Its impact on oil, inflation and interest rates is increasingly becoming a central driver of the global stock-market outlook.

 Oluwatosin Haruna